
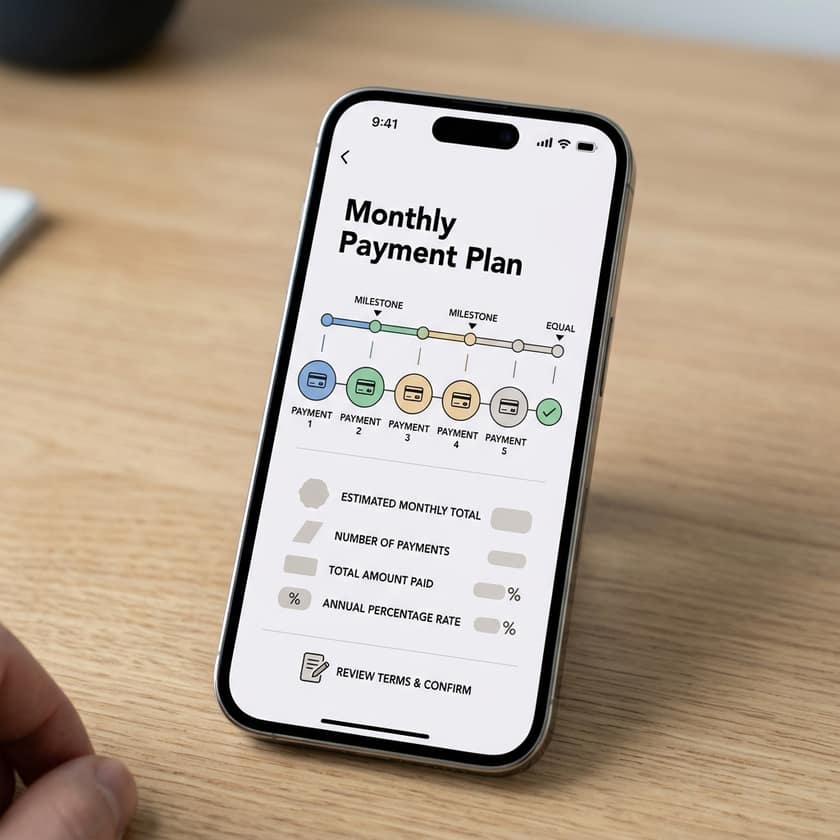
For many consumers, the latest iPhone represents a significant financial investment. With flagship models often costing hundreds of dollars, many people turn to installment plans to manage the expense. These programs allow you to spread the cost of a device over several months, often turning a large lump-sum payment into a more manageable monthly bill. Whether you are upgrading your current device or moving to a new ecosystem entirely, understanding how these financing options work is crucial for maintaining your budget and credit health.
Understanding Installment Financing Mechanics
Installment plans for smartphones function similarly to personal loans but are usually tied to specific retailer or carrier agreements. In the context of iPhones, the most common structure involves a 0% APR (Annual Percentage Rate) agreement. This means that if you adhere to the payment schedule and meet specific credit requirements, you will not pay any interest on the loan amount. Essentially, you pay the exact sticker price of the phone, divided by the total number of months in the contract, such as 12, 24, or 36 months.
However, it is vital to read the fine print. Some programs may offer promotional financing that reverts to a high interest rate if a payment is missed or if the balance is not paid in full by the end of the term. Always confirm the specific terms associated with your retailer or carrier before signing an agreement. A plan that looks affordable on paper can become expensive if you fall into the trap of high-interest credit lines later on.
Key Components of iPhone Payment Plans
| Feature | Typical Benefit | Key Consideration |
|---|---|---|
| Financing Rate | 0% APR | Subject to credit approval |
| Repayment Term | 12, 24, or 36 months | Determines monthly payment amount |
| Rewards | 3% Daily Cash Back | Often requires specific branded cards |
| Upgrade Cycle | Annual or Bi-annual | Check eligibility requirements |
| Payment Method | Automatic billing | Must keep account current |
Evaluating Your Financial Readiness
Before you commit to a long-term installment plan, consider the impact on your monthly cash flow. Even if the device payment is manageable at $24.95 or similar amounts, it is still an ongoing commitment that affects your discretionary income. Ask yourself if you truly need the most expensive model, or if a more budget-friendly option would suffice. Additionally, consider whether you are the type of user who upgrades every year or every three years. If you upgrade frequently, a trade-in program or a dedicated upgrade cycle program might be more cost-effective than a standard purchase plan.
Another factor to weigh is insurance and protection. Because the phone belongs to you—or is being financed against your credit—damage or loss can be financially devastating if you do not have coverage. Many installment plans offer integrated AppleCare or similar protection packages that can be bundled into the monthly payment. While this increases the monthly bill, it protects your investment against accidental damage, which is a common occurrence for mobile devices.
Tips for Smart Installment Shopping
- Always confirm the APR. Avoid plans that are not clearly labeled as 0% interest, as deferred-interest plans can be costly.
- Check for rewards. Look for programs that offer cash back, such as 3% daily rewards, which can effectively lower the total cost of the device over time.
- Review the trade-in value. If you are upgrading, check if the retailer offers an immediate credit for your old phone to reduce the total amount being financed.
- Read the fine print. Specifically, look for hidden fees or mandatory service requirements that might be attached to the installment agreement.
- Consider the duration. A 36-month plan lowers the monthly payment but ties you to that specific phone for a longer period. Ensure that matches your upgrade cycle.
When you choose a plan, you are effectively entering into a contractual agreement. Most providers will automatically charge the agreed-upon amount to your linked account or card. Be very careful to maintain sufficient funds in that account. A missed payment can lead to late fees, potential damage to your credit score, or, in some cases, the loss of the promotional 0% interest rate. Automated payments are convenient, but they require you to be vigilant about your banking balance to avoid overdrafts or returned payment fees.
Finally, look toward the future. Technologies change rapidly, and by the year 2026, the features available on current iPhones will likely be considered standard. Buying a high-end device on an installment plan is a great way to access current technology, but ensure the device you are choosing will hold up to your needs for the duration of the payment plan. Research the expected support lifecycle of the device and compare it against the length of your chosen installment term to ensure you are getting the most value for your money.