
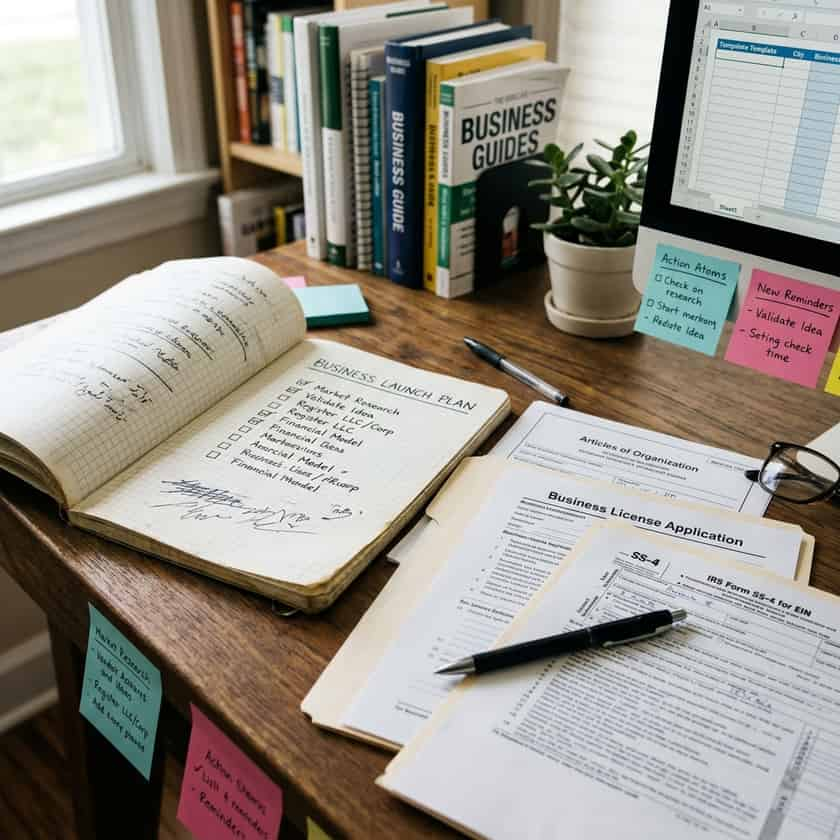
The Entrepreneurial Journey: Planning for Success
Starting a business is a transformative process that combines personal passion with market necessity. For many aspiring entrepreneurs, the journey begins with an idea, but success often relies on the discipline of the planning phase. Before you invest capital or leave your current employment, you must validate your concept. This means understanding if there is a genuine problem you are solving and whether customers are willing to pay for your solution. Market research during this phase is critical, helping you pivot away from non-viable concepts before significant resources are deployed.
By 2026, the landscape for small business owners has become increasingly sophisticated. Technology allows for rapid prototyping and digital testing, meaning you do not necessarily need a large budget to test your assumptions. Successful founders often start by creating a minimum viable product or service—a scaled-down version that allows you to gather real feedback. This iterative process is the hallmark of modern entrepreneurship, reducing risk while building a solid foundation for long-term growth.
Core Steps to Building Your Business Framework
- Conduct thorough market research to define your target audience and competitive landscape.
- Draft a business plan that outlines your goals, operational strategy, and financial projections.
- Choose an appropriate legal structure, such as an LLC or a sole proprietorship, considering tax and liability implications.
- Register your business name and secure all necessary local, state, and federal permits.
- Obtain an Employer Identification Number (EIN) from the IRS for tax and banking purposes.
- Open a dedicated business bank account to separate personal and company finances.
Selecting the right legal entity is more than just paperwork; it dictates how your business is taxed and your level of personal liability. A sole proprietorship is simple and inexpensive to form, but it offers no separation between your personal assets and business debts. Conversely, forming an LLC can provide a layer of protection. It is often advisable to consult with a legal professional or tax advisor during this stage to ensure your choices align with your long-term goals and asset protection strategies.
Financial Planning and Capital Management
Capital is the fuel for your business, but managing it wisely is what keeps the engine running. Many new entrepreneurs underestimate the startup costs, often focusing only on initial inventory or equipment. You must also account for operational overhead, marketing, taxes, and a reserve fund for contingencies. Creating a detailed cash flow projection is essential. This document helps you predict when money enters and leaves your business, allowing you to prepare for leaner months and avoid liquidity traps.
| Funding Source | Key Benefit | Potential Drawback |
|---|---|---|
| Bootstrapping | Full control | High personal risk |
| Bank Loans | Retain equity | Strict requirements |
| Angel Investors | Mentorship & capital | Equity dilution |
| Crowdfunding | Market validation | Time-intensive |
Marketing and Brand Visibility
Once your business is legally established and your finances are organized, the focus shifts to customer acquisition. Visibility is the biggest hurdle for new companies. In the current digital environment, your online presence acts as your storefront. This goes beyond having a website; it involves creating valuable content, engaging on social platforms where your audience resides, and implementing consistent search engine optimization strategies. Your marketing efforts should be focused on building trust with your target demographic.
Do not feel pressured to be on every platform immediately. It is better to have a deep, engaging presence on one or two channels than a shallow, fragmented presence across five. Focus on providing clear value, solving customer pain points, and soliciting reviews. Social proof, such as customer testimonials, is one of the most powerful marketing assets for a new business. Encourage early clients to share their experiences, as this authentic feedback can drive significant organic growth in your initial year.
Managing Operations and Growth
Operations management is about efficiency. As you scale, you will likely find that tasks which were easy for one person become bottlenecks. This is where systems and automation become vital. Using software to handle invoicing, customer relationship management (CRM), and project tracking allows you to spend more time on strategy and less on administrative maintenance. Remember that your time is the most valuable resource you have as a founder; treating it with the same respect as your cash flow is critical to sustainability.
Finally, stay adaptable. The market environment changes rapidly, and your ability to pivot is your greatest competitive advantage. Keep an eye on industry trends, listen to what your customers are saying, and be willing to refine your offerings. Starting a business is not a static event but a dynamic process of continuous improvement and adaptation. By staying organized, keeping your finances tight, and remaining focused on the customer, you can build a resilient business that thrives in the long term.