
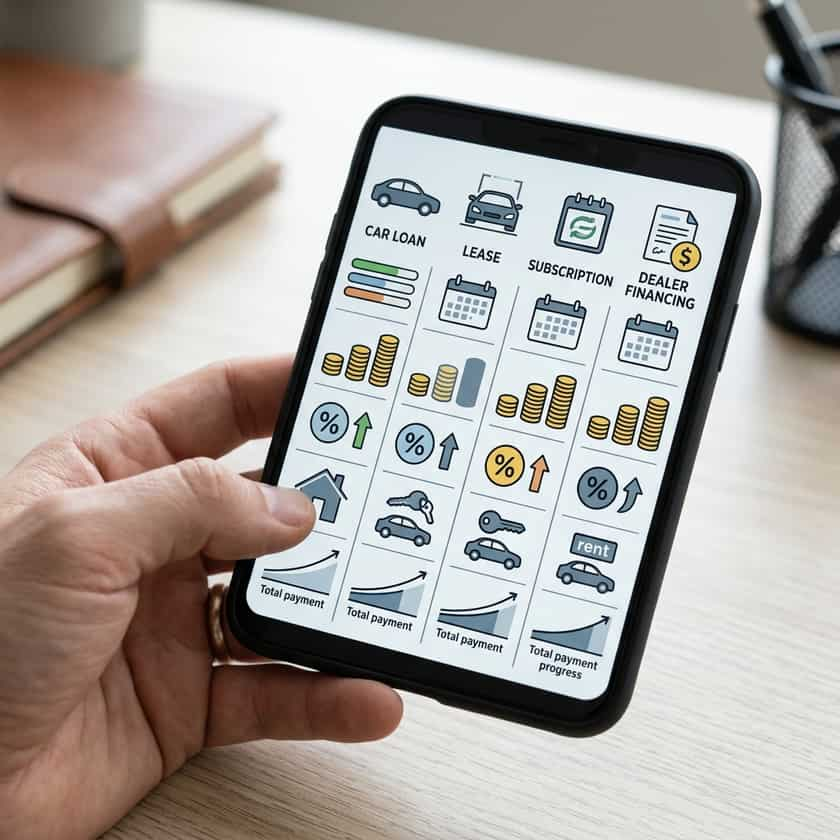
Understanding Pay-Monthly Car Financing
Monthly vehicle arrangements can include an auto loan, lease, subscription, or dealer-provided financing. Each creates a different combination of payment, ownership, mileage, insurance, maintenance, and end-of-contract responsibilities. A low advertised payment may depend on a down payment, trade-in, strong credit, limited mileage, a long term, or excluded taxes and fees. Begin with the vehicle and transportation need, then compare written offers using the same assumptions. Approval does not establish affordability, and the monthly payment alone does not show the total amount paid or the ongoing cost of operating the vehicle.
Key Types of Monthly Car Payments
- Auto loan: Borrowed funds are used to purchase the vehicle; compare amount financed, APR, finance charge, term, payment schedule, lien, and total of payments.
- Lease: Payments generally cover use of the vehicle under contract terms; review mileage, wear, insurance, fees, return, and purchase-option provisions.
- Vehicle subscription: Services and included items vary by provider; verify vehicle availability, insurance, maintenance, mileage, swaps, deposits, and cancellation terms.
- Dealer-arranged financing: The dealer may present credit from one or more lenders; compare it with outside offers and review every optional add-on.
- Buy here, pay here: The dealer provides or arranges in-house credit; examine APR, payment method, late consequences, repossession terms, and credit reporting.
With an auto loan, the amount financed may include the negotiated vehicle price, taxes, government charges, and optional products, reduced by cash down or trade-in credit. Interest and certain fees make up the cost of borrowing. A fixed-rate loan uses a rate that does not change under the contract, while other products may work differently. Payments generally reduce fees and interest before principal according to the agreement. Ownership is subject to the lender's lien until obligations are satisfied. Ask for the Truth in Lending disclosures and verify that the APR, finance charge, amount financed, total of payments, and payment schedule match the deal discussed.
A lease provides the right to use a vehicle for a specified period under mileage, condition, insurance, and payment terms. The payment may be lower than a loan payment for the same vehicle in some offers, but that outcome is not assured and does not mean the lease costs less overall. Review the amount due at signing, acquisition and disposition fees, mileage allowance and excess charge, wear standards, early-termination terms, and purchase option. Compare the net cost for the expected period of use, including insurance and likely mileage, rather than comparing only the displayed monthly amounts.
Comparing Your Monthly Payment Options
| Feature | Auto Loan | Lease | Subscription |
|---|---|---|---|
| Ownership path | Vehicle is purchased subject to any lender lien | No ownership unless a purchase option is exercised | Usually no ownership |
| Mileage | No contract mileage limit, though value changes with use | Allowance and excess-mileage terms commonly apply | Limits and charges depend on provider |
| Maintenance | Owner responsibility, with separate warranty terms | Responsibility and coverage depend on lease and warranty | Included services vary by provider |
| Insurance | Buyer must meet legal and lender requirements | Driver must meet legal and lessor requirements | Included or separate coverage varies |
| Ending the arrangement | Pay off, refinance, sell, or trade subject to lien | Return, buy, or follow other contract options | Cancel, renew, or switch under provider terms |
How to Calculate and Budget Your Monthly Car Payment
Set a vehicle budget from household cash flow rather than a universal percentage. Include the amount due at signing, monthly payment, insurance, fuel or charging, registration, taxes, parking, maintenance, tires, and a repair allowance. Also consider how income or essential expenses could change during the contract. For credit offers, compare APR, amount financed, finance charge, term, and total of payments. A longer loan can reduce the scheduled payment while increasing total interest and the period during which the balance may exceed the vehicle's value. Use a written worksheet so each offer is evaluated on the same basis.
Key Factors That Influence Your Monthly Rate
- Vehicle price and add-ons: Negotiate the vehicle and optional products separately from the payment discussion.
- Amount financed: Confirm what is included after the down payment, trade-in credit, taxes, fees, and add-ons.
- APR and finance charge: Compare the cost of credit, not only the interest rate or monthly payment.
- Term length: A longer term may lower the payment but increase total interest and negative-equity risk.
- Credit and approval: Lenders use their own criteria; a credit score does not establish a rate or approval.
- Contract conditions: Review late fees, prepayment, default, repossession, arbitration, and required insurance terms.
Obtaining written quotes from a bank, credit union, online lender, or dealer may provide comparison points before a final decision. A preapproval is conditional and can change after the lender verifies the vehicle, income, credit, or other information. It does not require a dealer to beat the rate or adjust the vehicle price. Keep the vehicle negotiation separate from financing when possible, and compare the dealer's complete written offer with outside offers using the same loan amount and term. Limit applications to those you intend to evaluate and ask how each inquiry may appear on a credit report.
The Role of Co-signers and Trade-ins
A co-signer becomes legally responsible for the debt and may face credit damage or collection if payments are missed; strong credit does not establish a particular approval or rate. Both people should receive and review the complete agreement. A trade-in can reduce the amount financed, but first verify its allowance, any existing payoff, and whether negative equity is being added to the new obligation. Compare the transaction with and without the trade-in so the vehicle price, financing, and trade value remain visible. Do not sign a blank form or rely on a verbal promise about later refinancing.
The right monthly arrangement is the one whose written terms fit the buyer's needs and budget after total costs and risks are considered. Compare multiple offers when practical, read required disclosures before signing, and confirm that the final paperwork matches the negotiated vehicle, price, add-ons, trade-in, APR, term, and payment schedule. If the payment works only by extending the term beyond a comfortable risk period or excluding essential operating costs, reconsider the vehicle or financing structure. Keep copies of applications, disclosures, contracts, warranties, receipts, and payment records.